Caseys shares plunged after earnings despite double-digit profit growth, but Bank of America views the pullback as a rare entry point for investors willing to look past short-term remodeling headwinds.
Caseys General Stores stock fell sharply by 14% following its latest earnings report, wiping out months of gains in a single trading session. This decline occurred despite the company delivering double-digit growth in both net income and EBITDA, prompting investors to question whether the selloff signals deeper issues or is simply a temporary setback.
Bank of America maintains its confidence in Caseys. The firm reiterated its Buy rating, contending that the market overreacted to short-term remodeling disruptions and a cautious consumer environment. Although Bank of America reduced its price target to $875 from $975, this still represents nearly 40% upside from the $629 share price at the time of the call.
In the first quarter of fiscal 2027, Caseys reported revenue of $5.68 billion, marking a 24.3% year-over-year increase, with inside same-store sales up 3.2% and in-store margins reaching 42.2%.
Remodeling drag and the real numbers
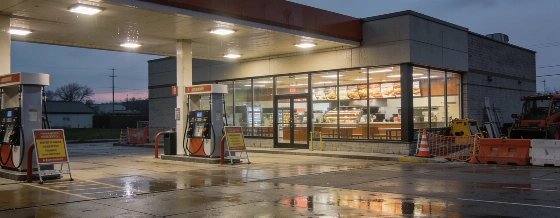
The primary factor behind the stock's decline is a wave of store remodels. Caseys is converting newly acquired CEFCO locations, resulting in some stores closing for up to six weeks to accommodate kitchen and foodservice upgrades. Bank of America estimates that this remodeling effort reduced inside same-store sales by about 25 basis points and fuel sales by 50 basis points in the first quarter, with the impact expected to continue through the fiscal third quarter.
Despite these headwinds, Caseys underlying business remains strong. In the fiscal first quarter, diluted earnings per share rose to $7.37, a 27.7% increase year over year. Net income reached $273.7 million, and EBITDA grew 17.1% to $485.1 million. Inside same-store sales increased 3.2% with a 42.2% margin, while fuel gross profit climbed nearly 20% to $446.9 million, even as gallons sold declined slightly. According to the official Caseys earnings release, these results exceeded the prior year's figures, when net income was $215.4 million and EPS was $5.77.
Foodservice and rewards drive the strategy
Caseys has evolved beyond a traditional gas station chain, developing a business model centered on prepared food, whole pizzas, and a growing rewards program. With nearly 3,000 stores across 19 states and 11 million rewards members, Caseys has positioned itself as a destination for more than just fuel.
The company's new three-year plan focuses on expanding food and beverage offerings, growing its store base, and improving operating efficiency. Management is maintaining its fiscal 2027 outlook, targeting 2% to 5% inside same-store sales growth, inside margins above 42%, and 8% to 10% annual EBITDA growth. At least 120 new stores are planned through acquisitions and new construction. In the first quarter, 24 CEFCO-acquired stores were remodeled, following approximately 50 conversions in fiscal 2026, as detailed in earnings-call coverage quoting management.
Management reported that remodeled CEFCO stores delivered approximately 30% uplift in prepared food and dispensed beverage sales, though these upgrades also created short-term operational drag, including 25 basis points of pressure on inside same-store sales and 50 basis points on fuel gallons.
Valuation and investor calculus
Bank of America's revised $875 price target is based on 18.9 times projected fiscal 2028 enterprise value to EBITDA, a premium compared to most convenience store peers. The firm attributes this to Caseys geographic reach, logistics capabilities, cost controls, and especially its exposure to higher-margin foodservice. Bank of America also raised its earnings estimates for the next three years, now projecting EPS of $21.77 in 2027, $24.06 in 2028, and $26.64 in 2029.
The post-earnings decline has widened the gap between Caseys current share price and what Bank of America considers fair value. While the firm's valuation stance is more conservative, it remains optimistic about the company's growth prospects. The payoff from remodeled stores could be substantial, with Bank of America estimating that upgraded locations typically achieve sales increases of about 30% over previous levels.
Recent volatility in energy markets has also brought attention to gas station operators. As reported earlier, rising oil prices and geopolitical risks have increased fuel costs, but Caseys has managed to expand its fuel margins even as volumes have declined.
What the numbers mean for households and portfolios
For U.S. consumers, Caseys transformation offers more food and convenience options, while signaling a strategic shift toward higher-margin products to offset potential softness in fuel demand. For investors, the central question is whether the remodeling impact is a short-term issue or an indicator of deeper challenges. Bank of America's analysis suggests the former, though risks remain if consumer caution or extended remodeling periods persist.
According to the U.S. Bureau of Labor Statistics, consumer prices for food away from home rose 5.4% year over year as of July 2026, while gasoline prices have remained volatile due to global supply concerns. These trends directly influence both Caseys cost structure and its customers' spending, making the company's emphasis on foodservice and rewards a strategic hedge against fuel market fluctuations.
Caseys General Stores is undertaking a significant transformation that extends beyond fuel sales. The company's willingness to accept short-term remodeling disruptions in pursuit of higher-margin growth represents a calculated risk not all competitors are prepared to take. For investors, the recent selloff appears to be more of a test of conviction than a fundamental warning sign. If Caseys achieves its foodservice and store upgrade goals, the stock could recover as quickly as it fell. However, the process carries risks, and the coming quarters will be critical in determining whether this transformation delivers the intended results or reveals new challenges.
Remodeling and store upgrades are common strategies among convenience retailers aiming to improve profitability, but their success depends on timing and execution. Upgrades that add kitchens and foodservice capabilities often require temporary closures, which can reduce sales in the short term but may drive higher traffic and margins once completed. For investors, understanding the balance between near-term disruption and long-term growth is essential when evaluating companies like Caseys that are investing heavily in transformation.