KenGen plans to cut its dividend by 16.67 percent for 2026, even as revenue rises and it keeps its lead in Kenya's power market. The move signals a shift in priorities for investors watching emerging market utilities.
KenGen is set to cut its dividend by 16.67 percent for fiscal 2026. This comes as a surprise for investors used to steady payouts from the Nairobi-listed power company. The board wants to pay a KES 0.75 dividend per share, down from KES 0.90. This is happening even though KenGen's revenue went up and it kept its top spot in Kenya's electricity market. Management is putting debt reduction and capital spending ahead of immediate shareholder returns. That's a trade-off more utilities in emerging markets are making as they deal with big infrastructure needs and tight balance sheets.
On September 22, 2026, KenGen shares closed at KES 10.75 on the Nairobi Securities Exchange. That was down 0.46 percent from the day before and well below the 52-week high of KES 13.10. The company's market cap stood at KES 71.22 billion. Over the past year, shares traded between KES 7.92 and KES 13.10. For U.S. investors who track global dividend stocks, the payout cut stands out. Revenue rose 6.4 percent to KES 59.7 billion for the year ended June 2026. But profit after tax slipped 1.2 percent to KES 10.35 billion. The gap between revenue growth and profit is shrinking. This is due to falling finance income and the need to manage borrowing costs, which dropped 12.1 percent to KES 2.0 billion.
Reuters market data shows KenGen has no trailing twelve-month dividend, with dividend-per-share fields reported as unavailable or zero, highlighting a recent compression in payouts.
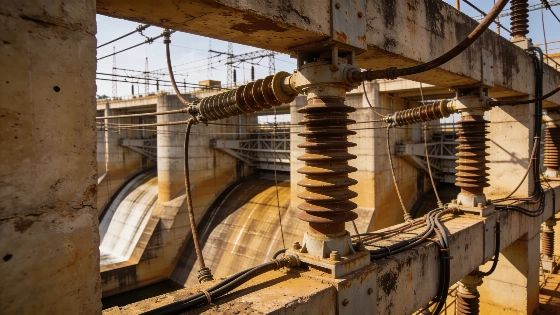
KenGen's strength is still in its power output. The company supplied 8,975 GWh to Kenya's national grid in fiscal 2026. That made up 57.2 percent of the country's total electricity supply. More than 90 percent of KenGen's power came from renewables. This helped drive revenue and kept KenGen at the center of Kenya's energy transition. National peak demand hit 2,549 MW in July 2026. KenGen's installed generation base was 1,786 MW. The company also cut its borrowings by KES 12.2 billion, bringing total debt down to KES 97.1 billion. This may help steady future cash flows, but it also means less cash is available for dividends in the short term.
KenGen's revenue for the year to June 2026 rose 6.4 percent to KES 59.7 billion. Operating profit climbed to KES 14.2 billion from KES 13.6 billion, according to a September 2026 business report. That same report says Kenya's peak electricity demand hit a record 2,549 MW on July 15, 2026. This shows the market KenGen serves is growing. KenGen's focus on renewables is clear: hydro makes up 45% of its installed capacity, geothermal 39%, and wind 2%. This mix puts KenGen at the heart of Kenya's energy transition.
KenGen is not alone in cutting dividends. Other utility and telecom companies have made similar moves, forcing investors to rethink how reliable payouts are in capital-heavy sectors. As reported earlier, Telus cut its dividend to free up cash for debt reduction. That move made investors look again at the trade-offs between yield and long-term financial health. For KenGen, cutting the dividend even as revenue rises shows the tension between funding growth, managing debt, and rewarding shareholders. This balancing act is now common across emerging markets.
KenGen's installed capacity reached 1,904 MW, with the majority of its power generated from renewables: hydro accounted for 45%, geothermal for 39%, and wind for 2%. This renewable mix is central to KenGen's strategy and Kenya's broader energy goals.
For context, the U.S. Federal Reserve's benchmark interest rate was 5.25-5.50 percent as of September 2026. This keeps global borrowing costs high and puts pressure on companies with big debt loads. KenGen reports in shillings and operates in Kenya, but the global environment of higher rates and cautious capital markets is shaping dividend decisions everywhere.
KenGen's dividend cut shows that even market leaders are feeling the squeeze from rising capital costs and the need to invest in infrastructure. Investors who rely on international dividend stocks for income need to look closely at cash flow and how companies set their capital priorities. Revenue growth no longer guarantees higher payouts-especially when management has to juggle demands from debt holders, regulators, and the urgent need to upgrade key infrastructure.
Dividend policy is a main tool for companies trying to balance growth, debt, and what shareholders want. In capital-heavy sectors like utilities, management has to weigh the appeal of cash payouts against the need for reinvestment and financial strength. For investors, knowing why a company cuts its dividend-whether it's lower profit, higher debt, or a shift in strategy-can help decide if a stock still fits an income-focused portfolio or if it points to deeper problems ahead.