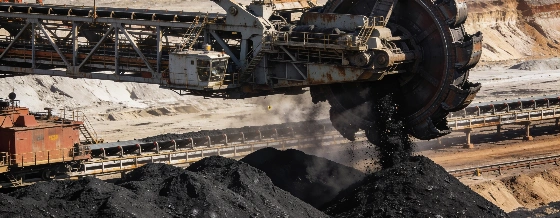
New Hope's profit tumbled 60 percent but the company surprised investors with a larger dividend. Higher costs and weaker coal prices weighed on results yet shares climbed as the market focused on the payout.
Investors largely overlooked a sharp earnings decline at New Hope, with shares rising 3 percent after the Australian coal miner declared a final dividend of $0.30 per share-significantly above market expectations. This announcement followed a 60 percent drop in adjusted net profit after tax for fiscal 2026, which fell to $162 million, or $0.19 per share, compared to the previous year.
New Hope reported saleable coal production of 11.5 million tonnes in FY2026, marking an 8% year-on-year increase, while coal sales rose 11.8% to 11.8 million tonnes.
Cost Pressures and Market Forces
New Hope's profit result was 35 percent below consensus estimates, primarily due to higher unit cash costs and increased depreciation. The company reported unit costs, excluding royalties, of $89 per metric ton-an 8 percent increase from the prior year. This rise was attributed to a temporarily higher strip ratio at the Bengalla mine and elevated diesel prices, which the company linked to the ongoing Iran war's impact on global energy markets.
Despite these challenges, New Hope did not issue formal earnings guidance. The company anticipates higher thermal coal volumes in the coming years as production ramps up at its New Acland mine, but the near-term outlook remains uncertain due to volatile input costs and fluctuating global energy demand.
Coal Demand and Supply Dynamics
According to a Reuters financial review, New Hope's net profit for FY2026 fell to A$161 million, more than halving from the previous year and coming in well below market expectations. The company attributed the margin squeeze to a 10% drop in realized coal prices to A$145.20 per tonne and a rise in unit costs to A$89 per tonne.
Looking ahead, regulatory and ESG pressures are expected to limit new supply. In New South Wales, a key source of high-quality coal, new coal mines have been banned, which could benefit existing producers such as New Hope and Whitehaven. New Hope's strategy depends on maintaining low-cost operations and leveraging constrained supply, even as global policy changes present long-term risks to the sector.
Portfolio Moves and Valuation
New Hope's acquisition of an additional 40 percent stake in the Bengalla mine in 2018, increasing its ownership to 80 percent, has further concentrated its exposure to thermal coal. The development of New Acland Stage 3 is projected to raise equity sales of thermal coal to about 13 million metric tons by fiscal 2029, up from approximately 11.8 million in 2026. The company also holds a 26 percent stake in Malabar Resources, owner of the Maxwell metallurgical coal mine in New South Wales, providing some diversification.
Bengalla and New Hope's other operations remain in or near the lowest quartile of the global thermal coal cost curve, offering a cost advantage over higher-cost, lower-quality producers. However, as a commodity producer, New Hope is a price taker and must rely on efficient, long-life mines to achieve returns above its cost of capital. The company's no-moat rating reflects the narrow gap between its return on invested capital and its weighted average cost of capital.
Investor Perspective
For U.S. investors monitoring global commodity stocks, New Hope's situation highlights how dividend policy can influence share prices even when operational results fall short. The company's fair value estimate remains at $6.20 per share, with the stock trading close to intrinsic value. The market's positive response to the dividend increase is similar to trends seen in recent shipping sector payouts, where investors have prioritized cash returns over short-term earnings volatility.
As of August 2026, the U.S. benchmark 10-year Treasury yield is near 4.2 percent, while global coal prices remain volatile amid evolving energy policies and supply disruptions. Investors in commodity-linked equities face increased risk as regulatory, environmental, and geopolitical factors play a larger role in shaping both supply and demand.
New Hope's decision to raise its dividend despite declining profits represents a calculated approach, relying on its low-cost mines and strong balance sheet to weather ongoing cost inflation and regulatory challenges. While the company's willingness to return cash to shareholders distinguishes it within a pressured sector, the long-term sustainability of this strategy will depend on its ability to control costs and adapt as coal's social license continues to erode.
Thermal coal is a fossil fuel primarily used for electricity generation. Its price and demand are shaped by global energy policy, environmental regulation, and the availability of alternatives such as natural gas and renewables. Producers with low-cost, high-quality reserves may remain profitable longer as higher-cost mines close, but the sector faces structural challenges as governments and investors push for decarbonization. Dividend payouts from commodity companies can provide income, but also reflect management's assessment of future cash flow stability and sector risk.