Nvidia projects a 70 percent revenue jump next year, Google Cloud sales soar 82 percent, and American Express raises its outlook after double-digit growth-giving investors new reasons to reconsider these blue-chip stocks.
Wall Street's appetite for growth is being tested as never before. Nvidia, Alphabet, and American Express are not merely weathering the current market's skepticism-they are redefining what it means to be a Dow heavyweight in 2026. While some legacy names in the index struggle to keep pace, these three companies are delivering results that demand attention from even the most cautious investors.
Alphabet raised its 2026 capital expenditure target to $195-205 billion, up from $180-190 billion, to accelerate investments in AI and cloud infrastructure.
Relentless Demand for AI and Cloud
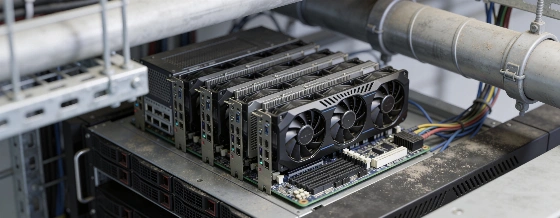
Nvidia's central role in the artificial intelligence boom is now firmly established. The company's latest guidance anticipates a 70 percent revenue increase in fiscal 2028, even as supply constraints limit its ability to meet full demand. Its Vera Rubin platform, which integrates CPUs and GPUs for advanced AI workloads, is already ten times more efficient than its predecessor. Despite more than doubling revenue year over year in the latest quarter, Nvidia's stock trades at just 14 times forward earnings-a valuation that would have seemed unlikely for a company with this growth profile a decade ago.
Alphabet, meanwhile, faces investor scrutiny over its substantial capital spending plans, but the financial results present a different perspective. According to a Reuters financial review, Alphabet reported Q2 2026 revenue of $119.8 billion, a 24% year-over-year increase, with Google Cloud sales rising 82% to $24.77-24.8 billion. The cloud division's operating margin reached 35.6%, and operating profit climbed to $8.8 billion, highlighting the profitability of its cloud and AI investments. Alphabet's AI platforms now process 22 billion tokens per minute, up from 16 billion the previous quarter. Nine million developers are building with Google's tools, and new products like Omni are driving rapid user engagement. Management maintains that the current investment cycle is essential to capture the next phase of AI-driven growth, even if it results in short-term pressure on free cash flow.
American Express Bets on Premium Consumers
Nvidia's Q3 2026 revenue guidance stands at approximately $108 billion, with a gross margin of 74.0% ±50 basis points, reflecting continued robust demand for its AI hardware.
Even as inflation affects household budgets, American Express's premium customer base has remained resilient. The company's decision to maintain earnings guidance while allocating additional revenue for future growth attracted some market skepticism, but this approach has proven effective in previous cycles. For investors, the result is a stock trading at just 15 times forward earnings-an unusually low multiple for a company with such brand strength and customer loyalty.
Market Performance and Valuation Gaps
As of the most recent quarter, Nvidia's market capitalization is $5.3 trillion, with a gross margin of 74.67 percent and a dividend yield of 0.24 percent. Alphabet's market cap stands at $4.1 trillion, gross margin at 60.94 percent, and dividend yield at 0.26 percent. American Express, while smaller at $219 billion in market cap, maintains a gross margin of 59.74 percent and a dividend yield of 1.09 percent. These figures underscore the scale and profitability that distinguish these companies from many other Dow components, some of which have struggled to achieve even single-digit sales growth in the same period.
For investors considering the balance between growth and income, the contrast is pronounced. While some blue-chip stocks offer higher yields or perceived stability, the companies propelling the index forward are those with the capacity to reinvest at scale and capture new markets. As ad-hoc-news market analysis notes, Alphabet's increased capital expenditures are directly linked to its aggressive expansion in AI and cloud infrastructure-a strategy that could further widen the gap with slower-moving peers.
What Sets These Leaders Apart
The ability to deliver both top-line growth and operational leverage distinguishes Nvidia, Alphabet, and American Express from the rest of the Dow. Each company has developed a business model capable of withstanding cyclical shocks and adapting to shifts in technology or consumer behavior. Nvidia's leadership in AI hardware, Alphabet's ecosystem of platforms and services, and American Express's premium network all create competitive advantages that are difficult to replicate.
It is important to note that while past performance does not guarantee future results, the mechanisms driving these companies' success are grounded in real demand, disciplined capital allocation, and a commitment to investing through uncertainty. For those seeking to understand why certain blue chips continue to outperform, the answer lies in their sustained focus on innovation, scale, and customer value-not just in quarterly results, but in the structural advantages that compound over time.
Understanding the distinction between a company's market capitalization and its revenue or profit is essential when evaluating stocks like Nvidia, Alphabet, and American Express. Market cap reflects the total value investors assign to a company based on its share price, while revenue and profit measure actual business activity and earnings. A high market cap relative to earnings can indicate strong growth expectations, but it also means investors are paying a premium for future potential. For long-term investors, balancing valuation with the durability of a company's competitive edge is key to making informed decisions in a market where not all blue chips are created equal.