Nvidia is sticking to its $4 trillion AI market forecast for 2030 but supply shortages and rising costs are putting pressure on margins and investor confidence
Nvidia's $4 trillion commitment to artificial intelligence is confronting the realities of supply constraints and a market that is moving faster than anticipated. While the company's latest earnings report set new revenue records, the underlying challenge is Nvidia's ability to meet surging demand-and the risks inherent in such an ambitious market outlook.
The Bank for International Settlements estimates that the world's five largest tech companies will invest more than $1 trillion in AI during 2025-2026, highlighting the unprecedented scale of the current investment wave.
Supply chain bottlenecks
Beneath the optimism, the data points to a market under strain. Nvidia's Data Center segment, serving hyperscale cloud providers and enterprise AI customers, generated $89 billion in the latest quarter-exceeding expectations by more than $3 billion. Gaming and physical AI units contributed an additional $7.2 billion. Overall, Nvidia's revenue increased 106% year over year, with adjusted earnings per share at $2.22, both surpassing analyst estimates.
However, the company's gross margin is projected to decline from 75% to 74% in the current quarter. Nvidia's guidance for the October quarter assumes no data center chip sales to China, reflecting the impact of U.S. export restrictions. At the same time, the cost of high-bandwidth memory has exceeded previous forecasts, and the three primary suppliers are unable to meet demand. Any further tightening could put additional pressure on margins. As reported by Reuters investigations, prices for AI chips in China have risen sharply due to a shortage of high-bandwidth memory (HBM), a critical component for AI accelerators, with supply remaining tight following stricter U.S. export controls imposed in December 2024.
CoreWeave and the demand crunch
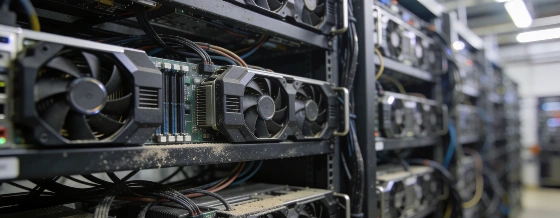
The supply-demand imbalance is particularly evident at CoreWeave, a specialized AI data center operator that depends almost entirely on Nvidia's advanced GPUs. CoreWeave's CEO has described a daily challenge to fulfill client demand, with every available GPU reserved multiple times over. Nvidia holds an 11.5% equity stake in CoreWeave, making it both the company's largest supplier and a significant investor.
High-bandwidth memory (HBM) is a multilayered memory technology that enables rapid processor access to vast datasets and is essential for AI accelerators. The global HBM market is effectively controlled by just three manufacturers: SK Hynix, Samsung, and Micron.
Investor risks and market realities
For investors, the risks are increasingly apparent. Nvidia's stock has surged on AI enthusiasm, but the company's future growth now depends on factors beyond its direct control: memory supply, export regulations, and the pace at which customers can expand new data centers. Goldman Sachs analysts have identified downstream power and data center capacity as the next likely bottlenecks, with equipment manufacturers and foundries already reporting record order backlogs.
China remains an unpredictable factor. With Nvidia's data center revenue from China now at zero due to export restrictions, Chinese competitors such as Huawei and Cambricon have raised prices on their own chips by up to 50%-not because they are gaining market share, but because they also face memory shortages. This indicates that Nvidia's absence has not simply shifted the market to lower-cost rivals.
As reported by Reuters, Jensen Huang has argued that the transition from information search to information generation is fundamentally altering the structure of demand for computing, a perspective echoed by several industry sources.
The ongoing AI data center expansion is testing the limits of infrastructure and supply chains across the sector, not just at Nvidia. Investors should monitor CoreWeave's rental pricing and Nvidia's margins for early indications of whether the company's optimistic forecasts can withstand the pressures of limited supply and rising costs.
According to the Federal Reserve, U.S. inflation remained above the central bank's 2% target in the most recent quarter, with core CPI rising 3.6% year over year as of July 2026. This persistent inflation continues to affect technology companies' input costs, including semiconductors and memory, and contributes to ongoing volatility in hardware pricing and supply contracts.
Nvidia's evolution from a chip supplier to a platform provider has given it significant pricing power, but that advantage depends on its ability to deliver hardware at scale. The company's $4 trillion AI market forecast is ambitious, but the critical test will be whether Nvidia can manage supply shortages, regulatory challenges, and depreciation risks without undermining the margins and investor confidence that have driven its growth. While current results support Huang's outlook, the margin for error is narrowing-and investor tolerance for missed targets is limited.
AI infrastructure spending extends beyond chips and servers. The expansion relies on a complex network of suppliers, power resources, and regulatory approvals. As demand for more advanced and reliable AI models accelerates, companies capable of securing both the necessary hardware and operational capacity will be best positioned. For investors, this means looking past headline forecasts to focus on the tangible constraints that may shape the next stage of the AI boom.