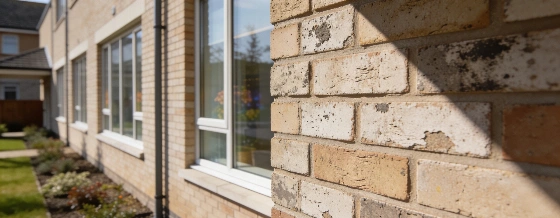
Target Healthcare REIT delivered its best results since going public in 2013, raising its dividend as property values and profits climbed in a tough market.
Target Healthcare REIT has raised its annual dividend after reporting its strongest total accounting return since its 2013 IPO. The trust posted a 12.0% total accounting return for the year ending June 30, 2026. In a sector where steady income is rare, this stands out.
The company, which owns care home properties, increased its annual dividend to 6.032 pence per share. That is up 2.5% from last year. Adjusted EPRA earnings fully covered the payout, with coverage at 108%. Target Healthcare REIT also set a new goal for the next year: a 3.0% increase to 6.212 pence per share. For investors who want income, this means higher payouts with strong financial backing.
The company announced its full-year results for the period ending June 30, 2026, on September 22, 2026, following a prior notice issued on September 16, 2026.
The dividend boost follows a year of solid financial results. EPRA net tangible assets per share rose 6.4% to 122.1 pence. Adjusted EPRA NTA was up 7.6%. Revenue slipped a bit to GBP72.1 million from GBP72.9 million, but total income jumped to GBP102.7 million. This was helped by GBP21.3 million in property revaluation gains and GBP9.2 million in realized property gains. Pretax profit climbed to GBP82.6 million, up from GBP60.8 million the year before.
At year-end, the property portfolio was valued at GBP924.1 million, a like-for-like increase of 4.9%. Contractual rents dipped to GBP61.1 million per year, but like-for-like rent growth hit 3.7%, mostly from rent reviews. The company credits inflation-linked rent increases and steady valuation yields for the rise in capital values. Investment activity also helped boost returns.
The market is still tough. The care home sector does not have enough supply, and competition for assets is strong. Still, the company points to long-term demand from an aging population as a key driver for both investors and operators. This trend gives the trust confidence it can keep growing its income, even as the wider investment market stays crowded.
Target Healthcare REIT highlighted that its results were supported by inflation-indexed rental growth, active asset management, reduced borrowings, and disposals of properties above book value. The company also noted that the care home sector remains structurally undersupplied, supporting long-term demand.
Shareholders welcomed the news. Target Healthcare REIT shares rose 2.3% to 115.40 pence in London trading on Tuesday. The trust's performance stands apart from other dividend-focused firms, like those in recent U.S. bank dividend stories, where payout growth often comes with less asset appreciation.
For context, the Bank of England's base rate was 5.25% as of June 2026. U.K. inflation had eased from its 2022 peak but stayed above the central bank's 2% target. These conditions have kept pressure on real estate yields and made inflation-linked income more attractive for investors looking to guard against rising costs.
A Morningstar/Alliance News report confirmed the board's target annual dividend for FY2027 at 6.212 pence per share, a 3.0% increase. This forward guidance shows the trust's focus on steady income growth for shareholders.
Target Healthcare REIT's results show that careful property selection and inflation-linked leases can deliver both capital growth and rising income. Many real estate investment trusts have struggled to keep payouts steady, but this trust has fully covered its dividend and set higher targets for next year. The business model is built for resilience, not short-term bets. For U.S. investors watching global REITs, the takeaway is clear: structural demand and lease terms matter as much as headline yield for lasting income.
Care home REITs work by buying and leasing specialized properties to care providers, usually under long-term contracts with rent increases tied to inflation. This setup can help protect income from short-term market swings. But it also brings risks, like regulatory changes, operator finances, and shifts in government funding for long-term care. As with any income investment, knowing the lease terms and tenant quality is key to judging both the stability and growth potential of future dividends.